
2 Year or 5 Year Mortgage

2 Year or 5 Year Mortgageの基本情報から最新動向までをわかりやすく整理しました。
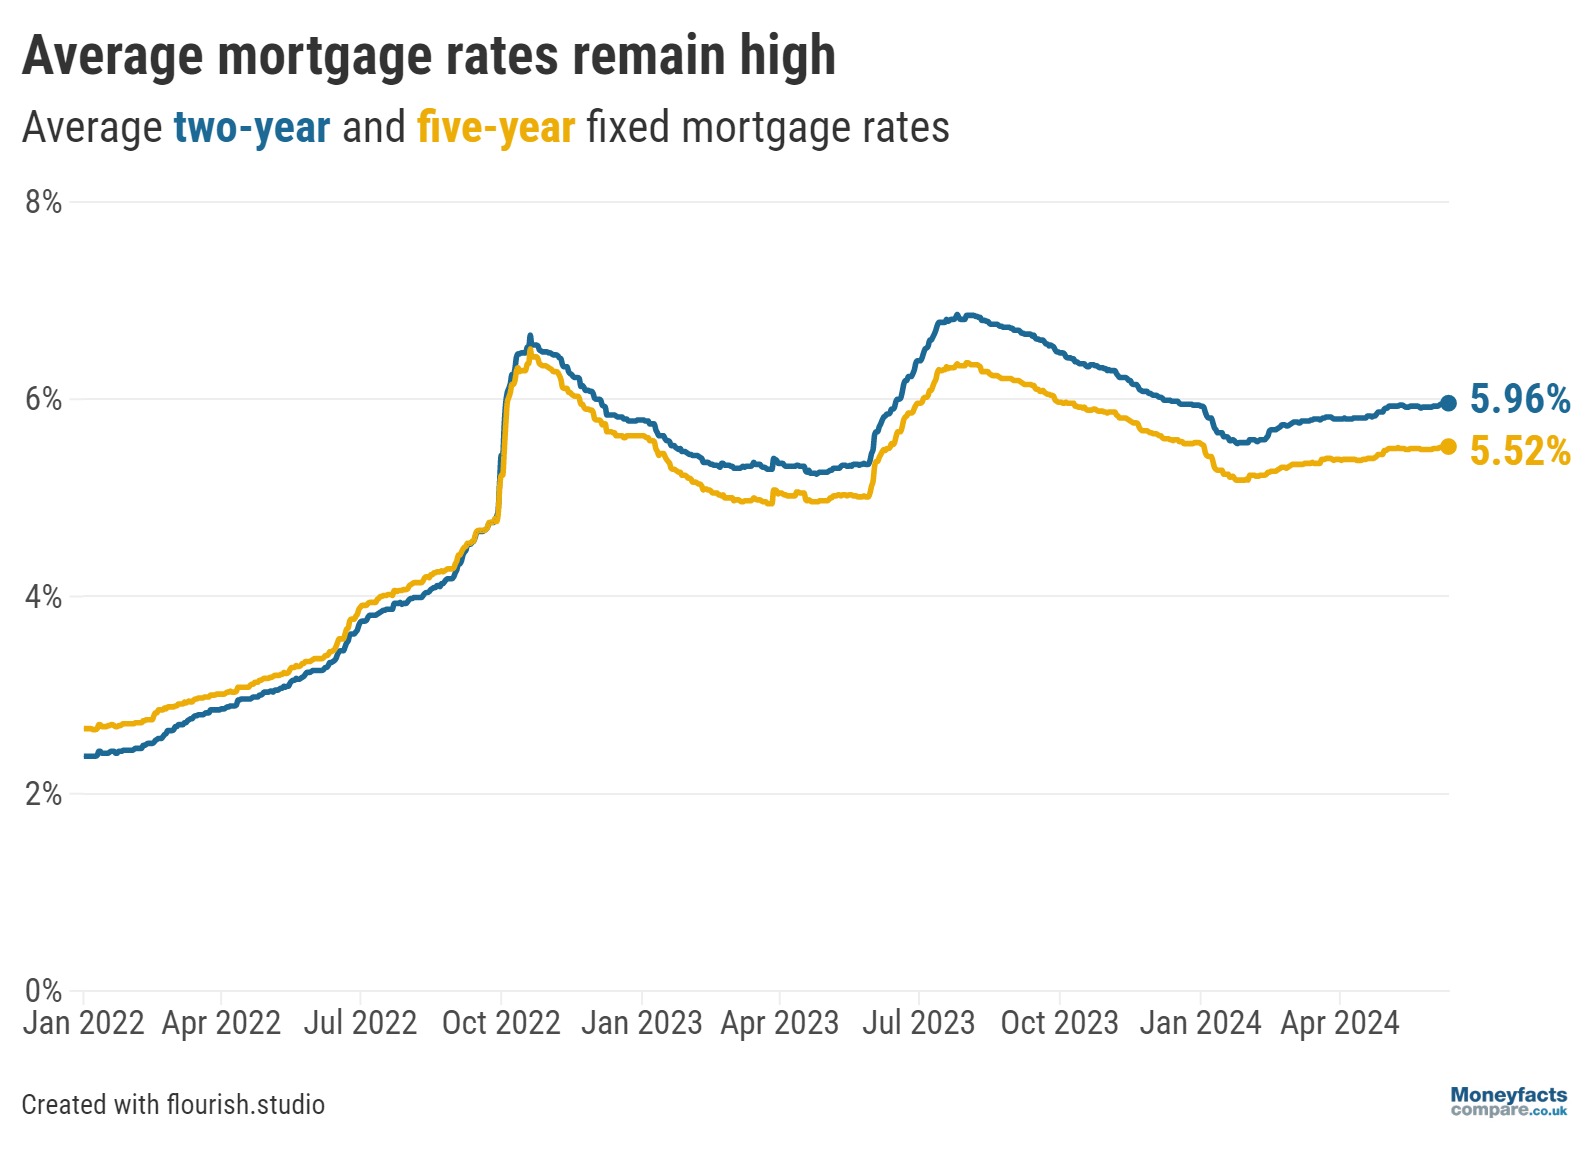
Why does this even matter? Because your mortgage term decides your interest rate and your flexibility. It’s not just a number; it’s your financial personality test.
Do you love a steal today, or do you crave peace of mind tomorrow? Spoiler: there’s no wrong answer—just your own brand of crazy.
The Two-Year Tango
Two years sounds fast. It’s like a Netflix binge—over before you know it. You lock in a low rate, but only for a blink.
Here’s the twist: after two years, you renew. That’s right; you dance with the bank again. If rates dropped, you win. If they soared? Ouch. It’s a gamble, but a thrilling one.
Quirky fact: two-year mortgages are the wild child of the mortgage family. They’re for risk-takers who live on the edge. Think of it as the “I’ll figure it out later” vibe.
The Five-Year Fortress
Five years is comforting. It’s like a cozy blanket in a chilly economy. You pay a slightly higher rate, but nothing changes for half a decade.
This is for planners. People who meal-prep on Sundays and actually floss. Your payment is predictable, like the Mrs. Smith across the street—boring, but reliable.
Funny detail: in some countries, choosing a five-year term makes you a veteran. Banks basically hug you. You’re their favorite customer, because you hate change.
グルメと旅を愛するフリーライター。全国各地の隠れた魅力を独自の視点から紹介します。
